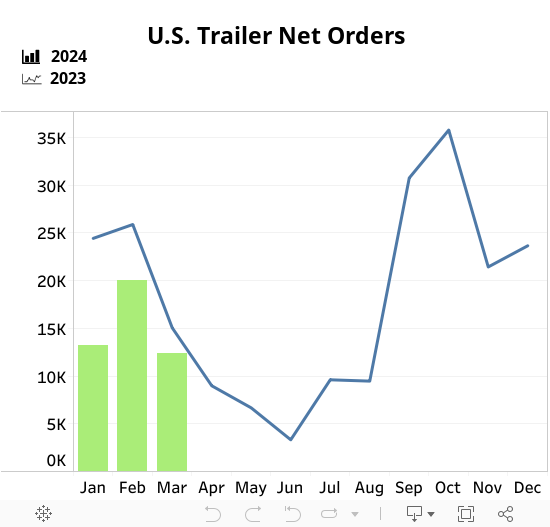
FTR reported an extraordinarily strong start to 2027 U.S. heavy-duty trailer order season as September net orders reached 43,059 units – the most since December 2022. Orders were up 78% month over month (m/m) and 385% year over year (y/y). Although weak prior-year comparisons magnify the increase, solid orders in both August and September point to substantial pent-up replacement demand, and some limited fleet expansion also is possible.
Earlier openings of 2027 order books and anticipation of further tariff-related trailer price increases may be encouraging fleets to place orders sooner. Meanwhile, the conclusion of the Class 8 pre-buy and regulatory uncertainty pending finalization of the EPA’s 2027 NOx compliance requirements could be shifting some near-term capital spending from power units toward trailers. Elevated equipment costs, however, will likely keep fleet investment selective.
In November, total trailer net orders were well above total production, increasing backlogs by 10,124 units (+12% m/m) to 92,213 units. Lower m/m production and growing backlogs pushed the backlog/build ratio up to 7.0 months, the highest reading since February 2024. This indicates some decreasing pressure on OEMs to scale back production in the near term.
The commercial vehicle market continues to see a disconnect between demand for trailers and demand for trucks. North American Class 8 net orders increased 2% y/y in September-November 2024 while U.S. trailer net orders dropped by 42% y/y during the same period. For-hire fleets have been prioritizing investments in new power units over trailers in 2024 YTD, likely influenced by reduced profitability or shifts in trade cycles. OEMs have notably cut back on production, but if 2025 trailer orders remain well below expectations, some OEMs may need to extend or deepen production cuts into next year.
Dan Moyer, senior analyst, commercial vehicles, commented, “Industry feedback reinforces the improving outlook. Rising quote activity and more requests for proposals indicate that fleets are becoming increasingly active in equipment planning. Trailer leasing utilization remains high while availability has tightened in certain markets, suggesting growing pressure on existing equipment capacity.
“Overall, the outlook points to stronger trailer demand in 2027, although September’s exceptional order pace may not be sustained. Elevated equipment costs, trade uncertainty, potential supply chain constraints, and competing fleet capital needs could temper the pace of recovery.”
Dan Moyer
Senior Analyst, Commercial Vehicles©2026 FTR Transportation Intelligence. All rights reserved.